
Why 95% of Startups Fail: Expert Tips to Build a Successful Business in India
First Startup
Nov 12, 2026
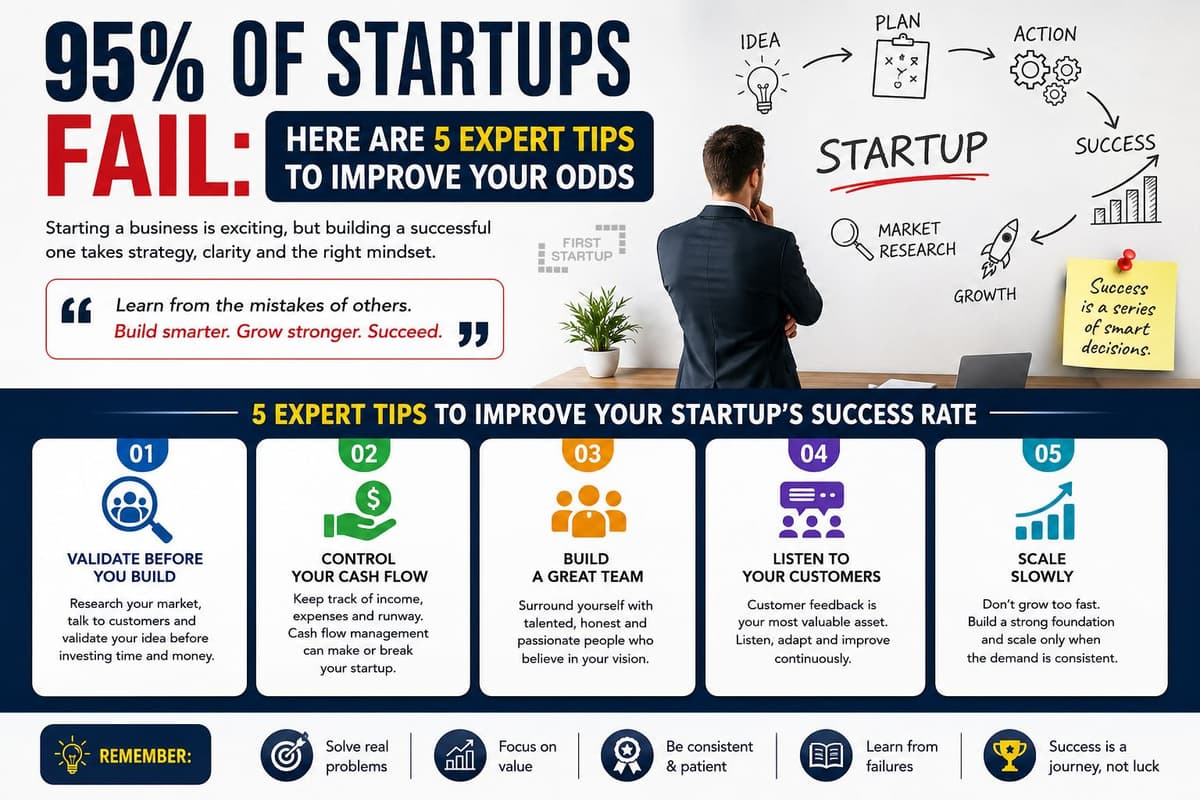
Starting a business is an exciting journey, but turning an idea into a successful company requires careful planning, consistent execution, financial management, and a clear understanding of the market. Many entrepreneurs launch startups with big dreams, but not every business survives the challenges of the competitive business environment.
The topic “95 Percent Startups Fail” highlights the difficulties entrepreneurs face while building a business. Startup failure can happen for several reasons, including a lack of market demand, poor financial planning, weak business models, ineffective marketing, and operational challenges.
However, startup failure is not inevitable. With the right strategy, proper legal registration, customer-focused products, and expert guidance, entrepreneurs can improve their chances of building a sustainable business.
In this blog, we will explore why startups fail and share practical expert tips to help entrepreneurs build and grow a successful startup in India.
Why Do 95 Percent of Startups Fail?
Startup failure is generally caused by a combination of business, financial, operational, and market-related problems. Many founders focus heavily on launching their products but overlook the important activities required to sustain a business.
Here are some common reasons why startups fail.
1. Lack of Market Research
One of the biggest reasons behind startup failure is launching a product or service without understanding customer requirements.
Entrepreneurs sometimes build businesses based on personal assumptions rather than actual market demand. If customers do not need the product or are unwilling to pay for it, generating revenue becomes difficult.
Expert Tip: Conduct proper market research before launching your business. Identify your target audience, understand customer problems, analyse competitors, and validate your business idea.
2. Poor Financial Planning
Financial mismanagement can create serious problems for startups. Businesses need sufficient funds to manage salaries, marketing, technology, rent, inventory, taxes, and daily operational expenses.
Some startups spend too much money during their initial stages without creating a realistic budget. Others fail because they do not maintain sufficient working capital.
Expert Tip: Prepare a financial plan before starting your business. Estimate initial investment, monthly expenses, expected revenue, and emergency funding requirements. Monitor cash flow regularly.
3. No Clear Business Model
A business idea alone cannot guarantee success. Every startup needs a clear business model explaining how it will generate revenue and remain profitable.
Without a defined pricing strategy, customer acquisition plan, and revenue model, businesses may struggle to maintain operations.
Expert Tip: Define your revenue streams, pricing structure, customer segments, and operating costs. Make sure your business model can support long-term growth.
4. Ineffective Marketing Strategy
Even a good product can fail if potential customers do not know about it. Many startups underestimate the importance of marketing and customer acquisition.
Without proper branding, online visibility, social media presence, and promotional activities, attracting customers becomes difficult.
Expert Tip: Build a marketing strategy that includes SEO, social media marketing, content marketing, paid advertising, and referral campaigns. Focus on channels that bring relevant customers.
5. Ignoring Customer Feedback
Customers play an important role in business growth. Startups that ignore customer feedback may continue offering products or services that do not meet market expectations.
Negative reviews, poor customer support, and unresolved complaints can damage a company's reputation.
Expert Tip: Regularly collect customer feedback, understand complaints, improve product quality, and provide reliable customer support.
6. Poor Team Management
A startup requires people with the right skills and commitment. Hiring unsuitable employees, unclear responsibilities, and poor communication can affect productivity.
Founders who try to manage every business activity themselves may also struggle to focus on long-term planning.
Expert Tip: Build a capable team, assign clear responsibilities, establish measurable targets, and create a positive working environment.
7. Legal and Compliance Problems
Many entrepreneurs focus on business development but overlook legal registrations and statutory compliance.
Depending on the business structure and activities, startups may need company or LLP registration, GST registration, trademark protection, accounting records, tax filings, and annual compliance.
Failure to meet applicable legal requirements can result in penalties, disputes, and operational difficulties.
Expert Tip: Choose the appropriate business structure and understand the registrations and compliances applicable to your business from the beginning.
Expert Tips to Prevent Startup Failure
Building a successful startup requires more than a good idea. Entrepreneurs need to make informed decisions, manage resources effectively, and continuously improve their business strategies.
Here are some practical tips to reduce the risk of startup failure.
1. Validate Your Business Idea Before Launching
Before investing significant money, test whether your product or service solves a genuine customer problem.
You can validate your idea through:
Customer surveys and interviews
Competitor research
Prototype testing
Trial services or minimum viable products
Pre-orders or pilot projects
This approach helps entrepreneurs understand market demand before making major investments.
2. Create a Strong Business Plan
A business plan provides direction and helps founders understand how their startup will operate.
Your business plan should include:
Business objectives and vision
Product or service details
Target customers
Competitor analysis
Revenue model
Marketing strategy
Financial projections
Operational requirements
Review your business plan regularly and update it as market conditions change.
3. Start Small and Scale Gradually
Many startups make the mistake of investing heavily before establishing a reliable customer base.
Starting with a smaller operation allows founders to test their business model, control expenses, and understand customer behaviour.
Once the business begins generating consistent revenue, entrepreneurs can expand their operations strategically.
4. Maintain Proper Accounting and Bookkeeping
Financial transparency is essential for every business. Without accurate financial records, founders may find it difficult to understand profitability, outstanding payments, expenses, and tax liabilities.
Maintain records of:
Sales and revenue
Business expenses
Customer payments
Supplier payments
Bank transactions
Tax liabilities
Employee salaries
Professional accounting and bookkeeping services can help startups maintain organised financial records and make better business decisions.
5. Choose the Right Business Structure
Selecting the right legal structure is an important step when starting a business in India.
Common business structures include:
Private Limited Company: Suitable for businesses planning to raise investment, issue shares, and build a scalable organisation.
Limited Liability Partnership (LLP): Suitable for businesses looking for a partnership structure with limited liability protection.
One Person Company (OPC): An option for an individual entrepreneur who wants to operate through a company structure.
Partnership Firm: Suitable for businesses established by two or more partners under a partnership arrangement.
Sole Proprietorship: A simple business structure for an individual operating a business in their own name.
Choose a structure based on ownership, investment plans, liability, compliance requirements, and future business goals.
6. Build a Strong Online Presence
A professional online presence helps startups build credibility and reach potential customers.
Important activities include:
Creating a professional website
Optimising website pages for SEO
Publishing useful blogs and articles
Maintaining social media profiles
Collecting genuine customer reviews
Running targeted digital marketing campaigns
Consistent online marketing can help businesses improve visibility and generate qualified leads.
7. Protect Your Brand with Trademark Registration
Your brand name, logo, and identity are valuable business assets. If another business uses a similar brand identity, it may create confusion among customers.
Trademark registration helps protect eligible brand elements and provides legal rights under applicable trademark laws.
Entrepreneurs should consider conducting a trademark search and applying for registration in the appropriate class.
8. Understand GST and Tax Compliance
Tax compliance is an important part of running a business in India. Depending on turnover, business activities, and applicable legal provisions, a startup may need GST registration and regular tax-related filings.
Entrepreneurs should maintain proper invoices, expense records, and accounting documents.
Professional guidance can help businesses understand applicable GST, income tax, TDS, and other compliance requirements.
9. Monitor Business Performance
Startups should regularly measure their performance instead of relying only on assumptions.
Important business metrics include:
Monthly revenue
Customer acquisition cost
Customer retention rate
Gross profit margin
Net profit
Cash flow
Conversion rate
Customer satisfaction
Tracking these metrics helps founders identify problems early and take corrective action.
10. Seek Professional Guidance
Entrepreneurs often need support with business registration, accounting, taxation, legal documentation, and statutory compliance.
Working with experienced professionals can help founders understand their responsibilities and avoid common administrative mistakes.
Important Registrations for Startups in India
Before starting operations, entrepreneurs should identify which registrations and licences apply to their business.
| Registration | Purpose |
|---|---|
| Company Registration | Establish a company as a legal entity |
| LLP Registration | Establish a limited liability partnership |
| GST Registration | Meet GST registration requirements where applicable |
| MSME Registration | Obtain Udyam registration if eligible |
| Trademark Registration | Protect an eligible brand name or logo |
| FSSAI Registration | Meet food business licensing requirements |
| Startup India Recognition | Apply for recognition if eligible |
| Shops and Establishments Registration | Comply with applicable state requirements |
Not every startup needs every registration. Requirements depend on the business structure, location, industry, turnover, and applicable laws.
How First Startup Can Help New Entrepreneurs
Starting a business involves several important steps, from selecting the right business structure to managing registrations and ongoing compliance.
First Startup provides professional business and management services to entrepreneurs, startups, and growing companies.
Our services include:
Private Limited Company Registration
LLP Registration
OPC Registration
Partnership Firm Registration
GST Registration and Compliance
MSME Registration
Trademark Registration
FSSAI Registration and Licensing
Accounting and Bookkeeping
ROC Compliance
ITR Filing
TDS Return Filing
Payroll Services
Our team helps entrepreneurs understand their registration and compliance requirements so they can focus on developing their businesses.
Get professional assistance from First Startup.
Website: https://www.firststartup.in/
Phone: +91 63956 22281
Email: [email protected]
Conclusion
The idea that 95 percent of startups fail highlights the challenges of entrepreneurship, but failure is not unavoidable. Businesses can improve their chances of success by understanding customer needs, preparing a realistic business plan, managing finances, building a strong team, and following applicable legal requirements.
A successful startup is built through continuous learning, customer satisfaction, financial discipline, and consistent execution.
If you are planning to start a business in India, take the time to validate your idea, choose the right business structure, complete the necessary registrations, and build a sustainable growth strategy.
Frequently Asked Questions (FAQs)
1. Why do 95 percent of startups fail?
Startups may fail because of poor market research, lack of customer demand, financial mismanagement, weak business models, ineffective marketing, and operational challenges. The exact failure rate varies depending on the definition of a startup, industry, country, and time period.
2. What is the biggest reason for startup failure?
Lack of market demand is frequently identified as a major reason for startup failure. A business may struggle if its product or service does not solve a genuine customer problem.
3. How can startups avoid failure?
Startups can reduce the risk of failure by validating their business ideas, maintaining proper financial records, understanding customer requirements, developing a strong business model, and monitoring business performance.
4. How much money is required to start a business in India?
The investment depends on the business type, industry, location, infrastructure, employees, and operating requirements. Some businesses can start with a relatively small investment, while others require substantial capital.
5. Which business structure is best for a startup in India?
Private Limited Company, LLP, OPC, Partnership Firm, and Sole Proprietorship are common options. The appropriate structure depends on ownership, liability, investment plans, and compliance requirements.
6. Is company registration necessary for every startup?
Not every business must register as a company. Entrepreneurs can choose from different legal structures depending on their business requirements and applicable laws.
7. Is GST registration compulsory for startups?
GST registration depends on applicable turnover thresholds, the nature of business activities, interstate supplies, and other conditions under GST law.
8. Why is accounting important for startups?
Accounting helps startups track income, expenses, cash flow, profitability, outstanding payments, and tax liabilities. Proper financial records support better business decisions.
9. Can a startup operate without trademark registration?
A business may operate without registering its trademark, but registration provides stronger statutory protection for eligible brand elements. Entrepreneurs should consider protecting their brand as early as practical.
10. How can First Startup help new businesses?
First Startup provides services such as company registration, LLP registration, GST registration, trademark registration, MSME registration, accounting, ITR filing, and business compliance support.